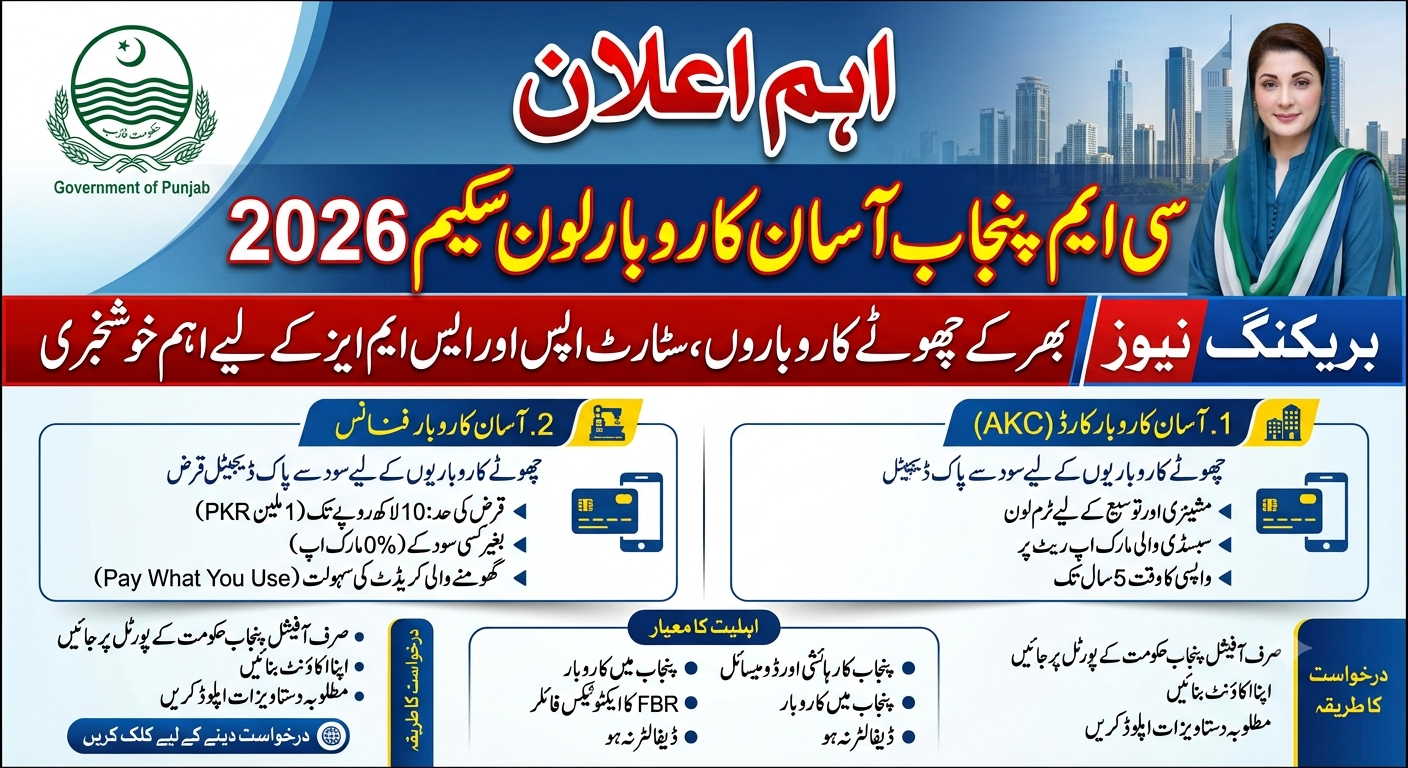
There has always been one obstacle to starting or expanding a small business in Punjab which is the cost of borrowing. The markup rates on commercial loans are such that they erode a startup at its very genesis and the small trader before it has even turned in a profit. Well for this reason the Government of Punjab has designed and initiated its CM Punjab Asaan Karobar Loan Scheme 2026 which aims at providing interest-free financing opportunities for small entrepreneurs, startups, and existing SMEs throughout the province.
In this article, we talk about what the scheme actually offers, who is eligible, what documents are required and how to apply — based on the program’s official framework so you know exactly what to expect before starting your application process.
What Is the Asaan Karobar Scheme?
Asaan Karobar Scheme is an SME financing plan powered by the Punjab government, implemented in partnership of Punjab Information Technology Board (PITB), Bank of PunjaB (BOP) and Punjab Small Industries Corporation (PSIC). The goal is to provide affordable and transparent business capital for the growing ranks of small traders, home-based businesses, freelancers and SMEs, but with no interest payments required.
The program is comprised of two separate components and one should not confuse the two:
1. Asaan Karobar Card (AKC) — For Small Entrepreneurs
- A revolving credit facility which is considered as an interest-free digital loan (not a one-off cash payout).
- Maximum loan facility: Up to 1 million PKR (10 lakh) will be disbursed through a digital SME card which can presumably be used via mobile app and pos channels.
- Releases of funds is on a milestone basis — generally the first 50% of an approved limit within six months and remaining thereafter after compliance checking.
- Unlike a single sum of a loan which would be fixed, since this is revolving credit you pay what you use and the limits become available again — just like a business credit line.
- Although the facility itself is free of interest, existing businesses (so-called brown field projects) may have to pay a small annual service fee — always check with the actual provision on the official portal before applying.
2. Asaan Karobar Finance — For Larger Business Needs
- Targeted towards older businesses which require larger capital for things like machinery, infrastructure or scaling.
- Provides term loans at reduced markup rates — subsidized by the government and usually well below market / commercial bank interest rates.
- Repayment tenures stretch up to five years, making EMI payments each month lower than what the customer would pay for a traditional bank loan.A note on loan numbers: You are likely to find various max amounts being quoted across different sites — some refer to PKR 1 million for the Card, others state tier finance brackets like Tier 1/Tier 2 going from a few to many crore rupees. These are two different schemes under the same scheme umbrella and numbers are updated periodically by government. But always before making a financial decision, check the actual limit for the product you are applying for on the official Punjab Government portal.
Who Can Apply? (Eligibility Criteria)
Be resident of Punjab, have domicile of Punjab as well as applicant must be a national of Pakistan.
The business should be based in Punjab.
Applicant’s age should usually fall within a specific working-age range (usually revolving between the early 20s to mid-50s) – check the latest limit on the portal
Be an active FBR tax filer or ready to fulfill the Tax registration within the time offered by this program.
Applicant who has registered number under his/her own CNIC and who does not have an expired CNIC.
You cannot be a loan defaulter or have an active default with some other bank.
Mainly a blueprint or feasibility report is required which should be straight forward, especially in new (greenfield) companies.
You are specifically directed to apply (youth and women entrepreneurs), some categories may not require documentation.
Documents You’ll Need
Have copies (light scans or photos, PDF/JPG) of you before applying:
- Valid CNIC (front and back)
- Proof of Punjab domicile/residence
- Proof of business premises — rent agreement or property ownership documents
- NTN / active tax filer proof from FBR
- Business plan or feasibility report (PSIC templates are often available on the portal)
- Passport-size photograph
- Bank account details
Requirements may differ slightly depending if you are applying for the Card or the Finance tier, check out your corresponding checklist on the portal to see your specific requirements.
How to Apply — Step by Step
- Sit Visit Punjab Government Official Asaan Karobar Scheme Portal. Avoid third-party sites that are not authorized to provide your personal or financial data.
- Create an account using your CNIC, full name and a mobile number registered in own name.
- Pick the scheme type — Asaan Karobar Card (micro, renewable credit) or Asaan Karobar Fin (macro, term mortgage).
- Fill out the application form with your name, business, and financial information.
- Submit documents — CNIC, domicile, business proof, NTN, and feasibility report.
- Submit and write down your reference number — this is important for you in the future to follow up on your application status.
- The verification stage—A special bank (generally Bank of Punjab) or PSIC officer may visit your business site and take your biometrics.
- Issuance and Release – Following the verification and approval, the card is issued or disbursed in batches.Processing time for each document verification and credit assessment ranges from two-week turnaround, to longer than a month inning, consider that your application will not get an instant approval.
Fees and Costs to Know
- The headline financing is interest-free (0% markup) on the Card, and subsidized markup on the larger Finance tier.
A nominal processing fee may apply, and this differs by tier — check the current fee schedule on the portal rather than relying on older articles, as fees are subject to revision.
Brownfield (existing) businesses may face a small annual handling charge on the revolving credit facility.
There are no hidden interest charges on the Card component if used and repaid within scheme terms — but late payment or default can lead to penalties and loss of the 0% markup benefit, so timely repayment matters.
Why This Scheme Matters
The biggest challenge for small traders, home-based sellers and first-time entrepreneurs wanting to formalise is usually collateral and high markup—both of which this scheme intends to address, or at least slightly ease. It strives to achieve this through a combination of digital verification and a government-backed guarantee framework.
Provide capital to the people who do not have traditional collateral
Encourage documented, tax-compliant business activity
Focus specifically on youth and women-led enterprises
Minimize reliance on unformal, expensive creditors
Important Precautions Before You Apply
- Use the official government portal only. Many unofficial sites duplicate scheme information (sometimes even word for word) and may not be accurate or up to date on rules, fees or contact details — some are partnered with totally unrelated ads, too. When an anchor mentions a figure or deadline, double-check that against the official source before acting on.
- Do not ever pay unofficial ad-hoc “processing agents” who promise you guaranteed approval — the scheme is built to be without intermediaries.
- It is not guaranteed that you will be allowed a loan after applying—it depends upon your documents being in order (such as your credit history and the data from site inspection)
- I mean its a business loan with repayment obligations — treat it like that, don’t consider it free money — think about cash flow before you decide to draw on the limit.Frequently Asked Questions
October 16, 2023 — Is the Asaan Karobar Card actually without interest? Yes the Card component is modeled as a 0% markup revolving credit line up to its approved limit. Please note that you may still be subject to minor processing or handling fees based on your business category, however.
Can a new business without any history apply? Yes, although you will basically need a decent feasibility / business plan because new (greenfield) applicants are monitored much more on their suggested proposal than any past business.
Card Card ya Asaan Karobar Finance mein kya falq hai? The Card is a small, interest-free ongoing credit line to use for everyday business purchases. Finance is of a higher term loan for capital expenditures such as plant and machinery or expansion, provided at a low (concessionary, not zero) markup.
Are loan defaulters eligible? No, persons with a current default on another bank loan are usually not accepted in this programme.
How long does approval take? It is not an instant-disburse product so keep this in mind that timelines vary based on documents validation & site visits, etc.
How do I check my application status? Via the official portal, with your CNIC and the reference number generated on time of submission.
Final Thoughts
CM Punjab Asaan Karobar Loan Scheme 2026 is more than a random palliative; it seeks to provide small businesses throughout the province with access to formal low-cost business financing. It is not a hack or a magic wand, it is not free money — this is a regulated credit facility with actual eligibility checks, proper documentation and full post-funding obligations. If you plan to apply, prepare your documents properly, check each and every detail from the official Punjab Government portal here before applying, and consider the funds as a means to make your business grow in a sustainable manner instead of getting struck with windfall.